The HomeHappy Team @ Canadian Mortgage Experts corporate team logo BC Mortgage Broker
Michael Anthony Lloyd & THe HomeHappy Team @ Canadian Mortgage Experts your BC Mortgage Broker - HomeHappy Strategy
Guiding you forward

Your Trusted Kelowna Mortgage Broker. Expert Financing Across the Central Okanagan.

In mortgage lending since 1988 · Independent BC broker since 1999 · 50+ lenders · 4.9★ from 170+ Google reviews · Michael Lloyd, BCFSA #MB614593

Buying and investing in Kelowna requires an advisor who understands the speed of our local market—not a detached, out-of-town bank call center. From first-time condo buyers downtown to luxury lakeview upgrades and strategic real estate portfolios, the HomeHappy team builds custom lending blueprints to help you win.

Navigating the real estate landscape of the Okanagan requires a strategy designed for a premium, fast-paced interior market. As a dedicated Kelowna mortgage broker team backed by over 260 verified client reviews on Google and Rate My Agent, we believe securing a home shouldn’t mean sitting in stuffy bank lobbies or settling for rigid corporate templates.

The big banks and out-of-town call centres treat Kelowna like any other postal code. Lenders don’t. A downtown waterfront condo, a family home in the Upper Mission and an acreage outside the city can each get a different answer from the same lender. With access to 50+ lenders and more than 25 years of BC files behind us, we know which lenders read your kind of property the way you need it read, and we build the mortgage around protecting your monthly cashflow.

Rate My Agent Top 100 Canadian Mortgage Broker, 2025

Ranked on verified client reviews: over 260 across Google and Rate My Agent.
Rate My Agent 2025 Top 100 Canadian Mortgage Brokers award badge for Michael Lloyd Read My Verified Kelowna Reviews

CommunityVotes Kelowna: Platinum, Four Years Running

The HomeHappy Team — CommunityVotes Kelowna 2026 Platinum Winner, Mortgages and Brokers — fourth consecutive year

The HomeHappy Team was named Platinum Winner in Mortgages and Brokers at the 2026 CommunityVotes Kelowna awards. It’s the fourth consecutive year we’ve taken Platinum in the category.

What makes this one worth mentioning is how it’s decided. CommunityVotes runs on public ballot — there’s no panel and no submission to write. Somebody has to think of your name and go vote. That’s a harder thing to earn than it looks, because a mortgage closes and then, for most people, the broker disappears. Four years in a row means clients remembered the file long after the keys changed hands and thought it was worth the thirty seconds.

Thank you to everyone in the Central Okanagan who voted.

Young couple making a heart shape with their hands outside their new Okanagan home

Central Okanagan Home Buying

From securing your very first condo to upgrading into a larger family home, we take the friction out of the process. We verify your documents and fully pre-qualify you before you tour weekend open houses with your Realtor, so you know your true buying power under the federal stress test and your offer stands out in a competitive Central Okanagan market.

Kelowna waterfront highrises lit up at night

Local Strata & Condo Expertise

Kelowna’s high-density market features unique lending variables that standard bank employees often miss. Out-of-town underwriters regularly stumble over local strata form analysis, self-managed complexes, and restrictive rental bylaws. We specialize in local condo financing, maintaining direct access to lenders who understand Kelowna’s unique residential towers and townhome developments.

By receiving the HomeBrew monthly report from the HomeHappy Team @ Canadian MOrtgage Experts, you can track your home's value, your mortgage, your equity, and whether making a change makes sense.

Renewal Review & Rate Hold

Leaving your mortgage untouched until renewal day can be a five-figure mistake. We watch the market for you, send you a monthly report on your home and mortgage, and start your renewal review early enough to hold a rate up to 120 days before maturity. If high-interest debt is squeezing your budget, we can roll it into one mortgage payment to free up your monthly cash flow.

While the big banks look at local real estate through rigid corporate filters, our HomeBrew reports track your local market month by month.

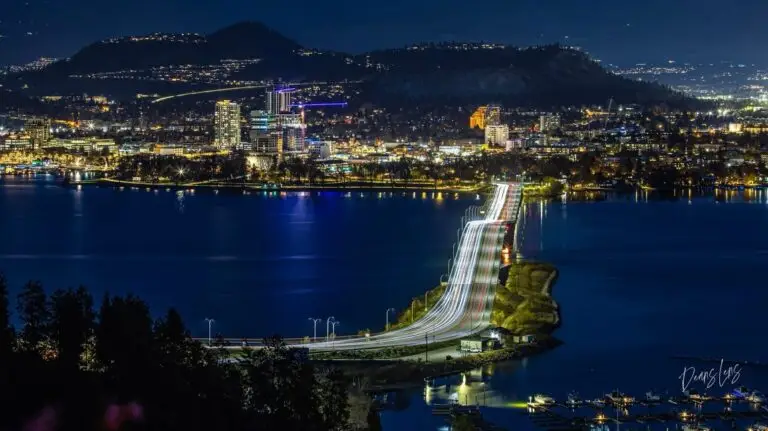
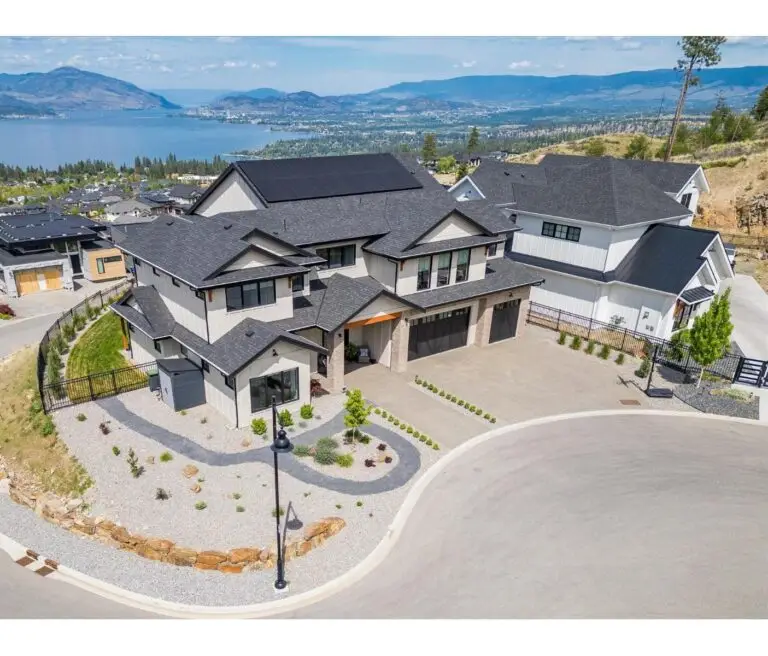
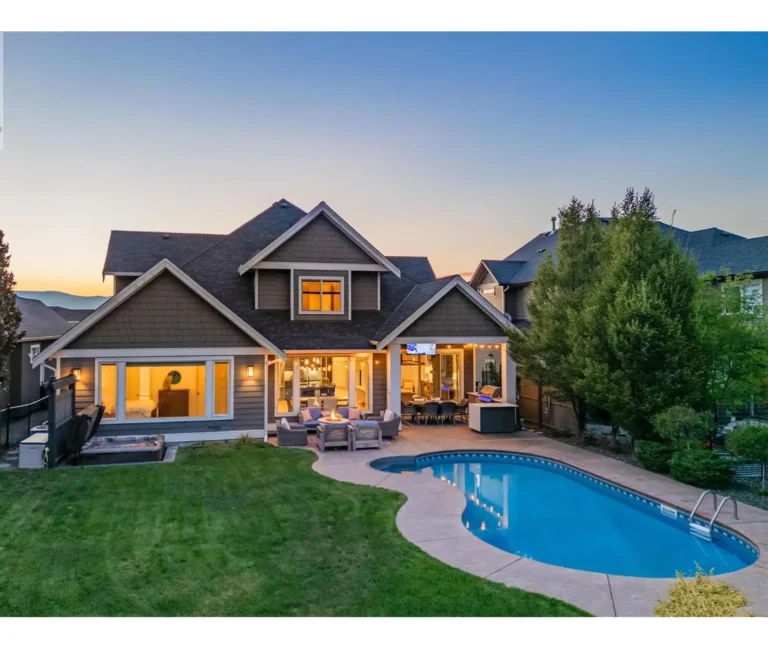
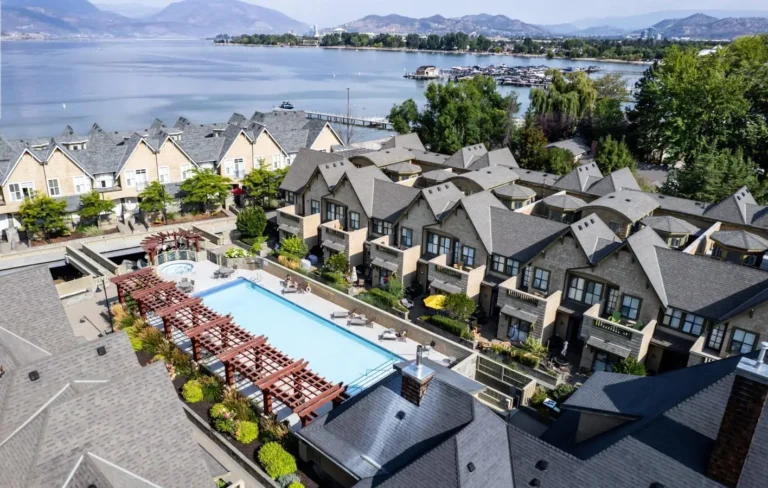
Take a look through our Kelowna portfolio gallery below to see the diverse property markets—from vibrant downtown developments to scenic hillside family homes—where we actively manage equity, protect monthly cashflow, and guide homeowners all the way to mortgage freedom day.

Micro units in Kelowna.   Kelowna has embraced the micro suite. Cambridge House, Central Green, Ella and the new Revo Kelowna all include condos of roughly 300 to 315 square feet, and the Sole buildings run from about 300 to 450. Many lenders set a minimum unit size and won’t lend below it, so financing a suite this small is hard to find. Last October a client came to me to refinance a rental micro condo of just over 300 square feet. I knew which lenders would consider it. She pulled equity out and used it to consolidate her other debts.

HomeBrew, The HomeHappy Team's monthly mortgage digest

Unlock Your Custom HomeBrew Analysis

Standard bank apps give you basic numbers, but they don’t give you a strategy. As your Kelowna mortgage broker team, we look far beyond basic interest rates with our HomeBrew wealth-tracking platform. Every month it tracks Okanagan property values, your true net equity cushion, and proactive debt-restructuring options, well before renewal pressure peaks.

Don’t navigate the fast-paced local real estate landscape blindly. Click below to see exactly how our custom roadmap works to protect your monthly baseline cashflow, optimize your property wealth, and fast-track your path to mortgage freedom day.

Kelowna Mortgage Questions We Actually Get Asked

Kelowna opted out of the short-term rental rules. Can I count Airbnb income to qualify now?

Be careful here, because the change is narrower than the headlines suggest — and the mortgage answer is different from the zoning answer.

Effective June 1, 2026, Kelowna became the first and only municipality in British Columbia to opt out of the province’s principal residence requirement for short-term rentals. But that only applies to properties rezoned into the City’s new STR sub-zone. Everywhere else in Kelowna, the old rule still stands. So the first question on any property isn’t whether Kelowna opted out — it’s whether that specific address is on the approved list. Verify it with the City of Kelowna before you write an offer, not after.

The mortgage side is more conservative than people expect. Most lenders treat short-term rental income cautiously or won’t count it at all, and those that do generally want a documented history rather than a projection. A pro forma from a listing agent is not income.

And there’s a lesson worth taking from recent history. When the provincial rules took effect in May 2024, Kelowna’s short-term rental inventory fell from roughly 2,400 units to about 400. People who had qualified on that income didn’t stop owing the mortgage. A bylaw can remove your revenue; it can’t remove your payment. We’ll happily structure around short-term rental potential — we won’t build your qualifying on it.

I’m buying acreage outside Kelowna. Does that change the mortgage?

Considerably, and it catches people out on properties in Joe Rich, Ellison, and the rural edges of the Central Okanagan.

Most lenders will only finance against the house and a limited amount of land — commonly the first five acres — with the balance treated as having little or no lending value. So a ten-acre property can appraise well and still support a much smaller mortgage than the purchase price suggests. Add well and septic, which usually mean water potability and flow tests, and an outbuilding or two that may not count toward value at all, and the gap between price and financeable value can be significant. Agricultural Land Reserve status narrows the lender list further.

None of this makes acreage hard to finance. It makes it a file where the lender has to be chosen before the offer, not after.

My income is seasonal. Can I still get a mortgage in Kelowna?

Yes, and it’s common enough here that it’s a normal file rather than an exception — hospitality, tourism, wineries, construction, and the trades all run seasonally in the Okanagan.

What lenders want is a pattern rather than a paycheque. Generally that means a two-year history in the same line of work, with income averaged across the full year rather than taken from a peak month. If you’re paid through a corporation, or your T4 understates what the business actually earns, the picture changes again — see our guide to self-employed mortgages in BC.

The mistake we see is people applying during their strong months and being surprised the lender doesn’t annualize it. Bring us the whole year.

Should I be worried about a strata’s depreciation report?

You should read it, and most buyers don’t.

A depreciation report sets out what the building will need and when, and whether the contingency fund can pay for it. If it can’t, the shortfall arrives as a special assessment — and a special assessment lands on you whether or not you knew it was coming. Lenders and insurers both look at strata documents on higher-ratio files, and a building with a large, unfunded, near-term item can affect approval as well as your budget.

Kelowna has a lot of strata stock built in the 2000s now arriving at the age where envelope and mechanical work comes due. Read the report and the last two years of minutes. If they concern you, that’s information worth having before the subject removal date rather than after.

Is buying a second home or recreational property different?

Yes, in ways that are easy to plan for and expensive to discover late. Down payment requirements are generally higher on second homes than on a principal residence, and higher again on properties that are seasonal, off-grid, on leased land, or without year-round road access. Lender appetite varies more on this category than almost any other, and the differences are structural rather than a matter of rate.

The building I’m buying in has Airbnbs. Does that affect my financing?

Often, yes — and this is the part that surprises people, because it isn’t about you or your file at all.

Lenders assess the building, not just the borrower. Where a strata has a high concentration of short-term rental units, a lender may decline the property outright regardless of how strong the application is. The concern is resale liquidity and the stability of the strata’s finances, not whether you personally intend to rent it out.

What makes this genuinely difficult to predict is that published lender guidelines don’t settle it. We have taken a resort-area strata file to a lender whose broker guidelines explicitly state they finance short-term rental properties, and been declined once their underwriter looked at the building itself. Policy documents describe what a lender will consider. They don’t tell you what a specific underwriter will do with a specific address.

The practical consequence is that a resort or STR-heavy strata needs the lender identified before the offer, not after — and needs a broker who has actually placed one, rather than one reading the same guideline you could read yourself.

Do you rate match?

No, and here’s why. Rate matching means you had to find a better offer before your broker would move. We shop 50+ lenders before we ever give you a number, so the first rate you see from us is the strongest one we can find for your file. There’s no haggling and no “let me see what I can do.”

And rate is only part of the decision. A slightly lower rate with a harsh penalty clause or tight prepayment limits can cost you more over the life of the mortgage. We explain how we weigh that in The GIC Question or the Financial Planner Question.

Where Else We Work

Central Okanagan buyers rarely search one city. Plenty of files start in Kelowna and end in West Kelowna or Penticton once the numbers get real, and we see the reverse just as often — families moving up from the Lower Mainland for the space. The financing questions follow the property type, not the postal code.
Stop Stressing over Bank Math. Get the Monkey Math App!

Monkey Math, The HomeHappy Team's mortgage app for your phone

Redefine Mortgage Math. Put the Simplicity in Your Pocket.

Love the calculators on our site? Take the effortless simplicity of Monkey Math with you…

Scan or Tap to Download (FREE)

BC Mortgage Experts

Let's chat!

Grab a coffee and let’s connect face-to-face from the comfort of your own couch. We’ll jump on a secure video call to review the numbers and build your custom property plan together. Click here to lock in your time.

Kelowna Mortgages: Your Bank, a Transactional Broker, or HomeHappy

Where you get your mortgage changes what happens to it. Here is how the three options compare for a Kelowna purchase or renewal.

Your bank or bank repA transactional brokerHomeHappy
Lenders you can reachThe bank’s own products only, from a branch or a mobile mortgage repSeveral lenders, depending on the brokerage50+ lenders from one application
A strata with a funding shortfall or many AirbnbsOne policy applied to the buildingDepends on the broker’s lender listLenders assess the building as well as you, so we check it before you commit
Acreage, seasonal income or a second homeOne set of rulesVariesLender appetite differs a lot on these, so we match the file to a lender that reads it well
Pre-qualificationOften a rate hold on numbers you stateVariesDocuments reviewed first, answer 24 hours after a complete package
After closingThe mortgage sits until the renewal letterFile closed, paid, forgottenGoes into HomeBrew, with a strategy conversation by 6 months before renewal
How you meetA branch, or a mobile rep who comes to youVariesVideo or phone, from our West Kelowna base
Kelowna Mortgage Broker

Why Choose HomeHappy as Your Kelowna Mortgage Broker?

Most lenders treat a mortgage as a one-time transaction, disappearing the moment your papers are signed. As your dedicated Kelowna mortgage broker, we play the long game—staying by your side to actively manage, optimize, and restructure your debt from day one all the way to your ultimate mortgage freedom day.

By combining our multi-decade track record in the Okanagan with proactive financial strategy, we ensure your mortgage continuously evolves to protect your cashflow and maximize your wealth for the life of your loan.

Kelowna real estate, from both sides
Every quarter, Mike sits down with Dallas Crick of Hilbert & Crick Real Estate Group to talk about the Kelowna market from both sides of a purchase, the home and the mortgage. Start with what a quiet market means for your mortgage, or watch the full video series.

The HomeHappy Team @ Canadian Mortgage Experts

Address:
3954 Beachview Drive West Kelowna, BC V4T2K1
URL: www.homehappy.ca/kelowna-mortgage-broker
HappyChat, the monthly eNewsletter from The HomeHappy Team @ Canadian Mortgage Experts: a quick synopsis of the mortgage rate and product world.

Join our Monthly e-Newsletter

Website HappyChat Sign Ups