The HomeHappy Team @ Canadian Mortgage Experts corporate team logo BC Mortgage Broker
Michael Anthony Lloyd & THe HomeHappy Team @ Canadian Mortgage Experts your BC Mortgage Broker - HomeHappy Strategy
Guiding you forward

Your Trusted Penticton Mortgage Broker. Expert Financing Across the South Okanagan.

In mortgage lending since 1988 · Independent BC broker since 1999 · 50+ lenders · 4.9★ from 170+ Google reviews · Michael Lloyd, BCFSA #MB614593

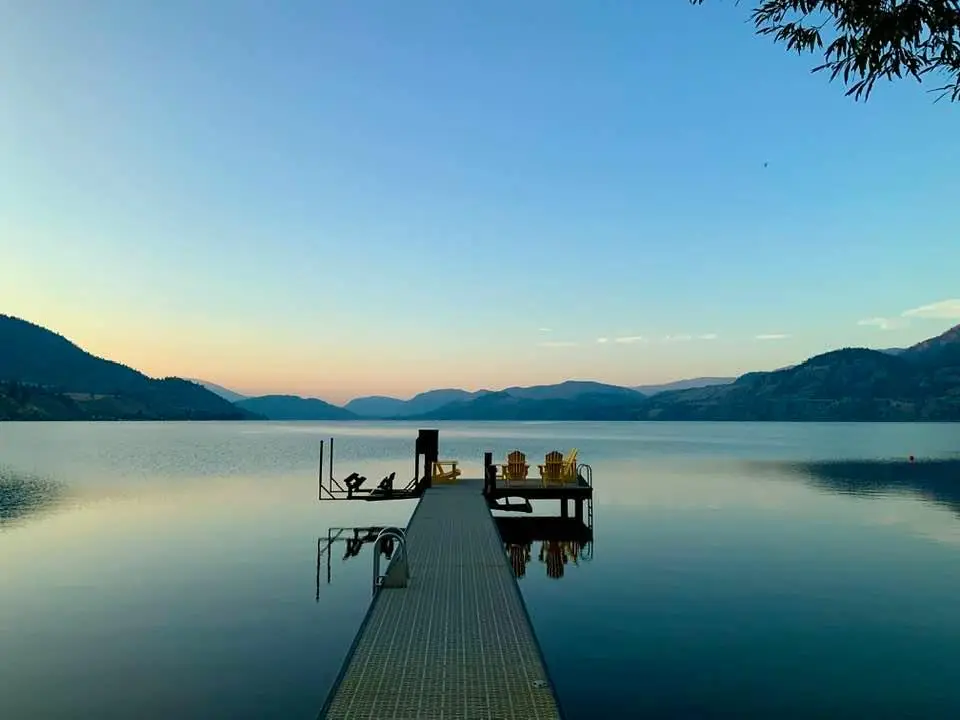
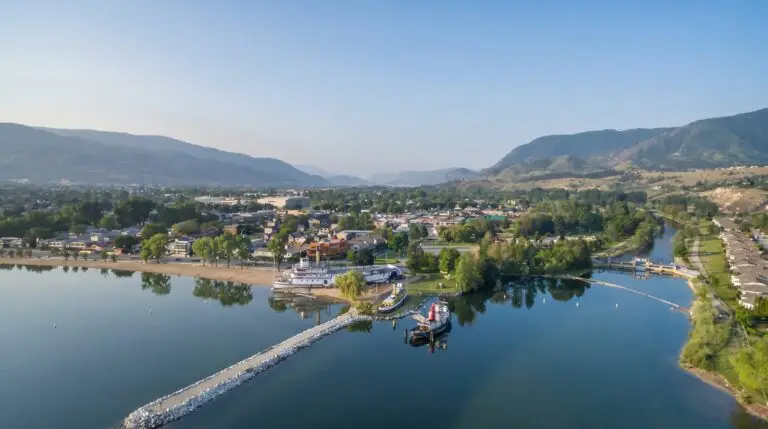
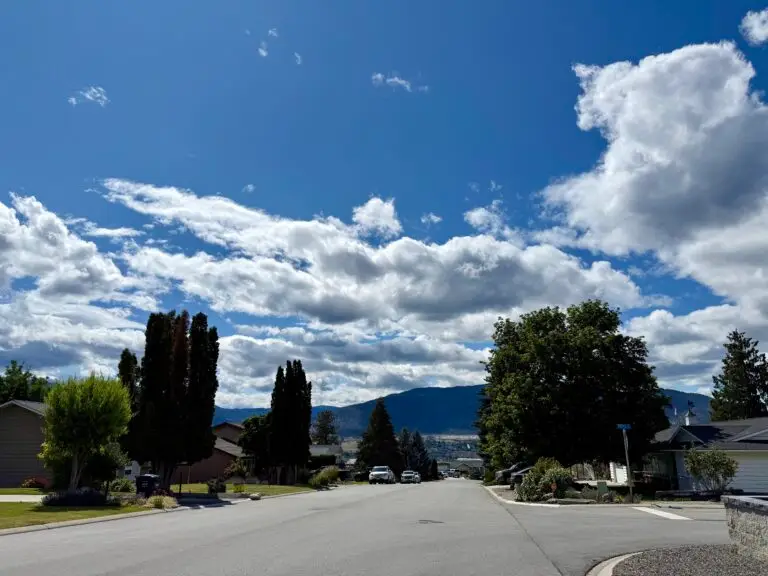
Having grown up right here in Penticton (in fact, that photo on the right is the actual view from my mom’s place!), I know firsthand what makes the South Okanagan so special. Buying and investing here requires an advisor who truly understands the rhythm of our local market—not a detached, out-of-town bank call center. From first-time buyers looking near Skaha Lake to luxury lakeview upgrades along Naramata Road, the HomeHappy team builds custom lending blueprints backed by a lifetime of local insight to help you win.

Navigating the real estate landscape of the South Okanagan requires a strategy designed for a highly desirable, fast-paced valley market. As a dedicated Penticton mortgage broker team backed by over 260 verified client reviews on Google and Rate My Agent, we believe securing a home shouldn’t mean sitting in stuffy bank lobbies or settling for rigid corporate templates.

The big banks and out-of-town call centres treat Penticton like any other postal code. Lenders don’t. A lakefront condo near Okanagan Beach, a family home in Wiltse Flats and a leasehold property near Skaha Lake can each get a different answer from the same lender. With access to 50+ lenders, we know which ones read your kind of property the way you need it read, and we build the mortgage around protecting your monthly cashflow.

Rate My Agent Top 100 Mortgage Brokers Canada, 2025

Ranked on verified client reviews: over 260 across Google and Rate My Agent.
Read My Verified Penticton Reviews
A family is moving in to their new home in Penticton, the HomeHappy Team @ Canadian Mortgage Experts helped them find the perfect mortgage plan to make it a reality.

South Okanagan
Home Buying

From securing your very first condo to upgrading into a larger family home, we take the friction out of the process. We verify your documents and fully pre-qualify you before you tour weekend open houses with your Realtor, so you know your true buying power under the federal stress test, your offer stands out in a competitive South Okanagan market, and your down payment is protected from day one.

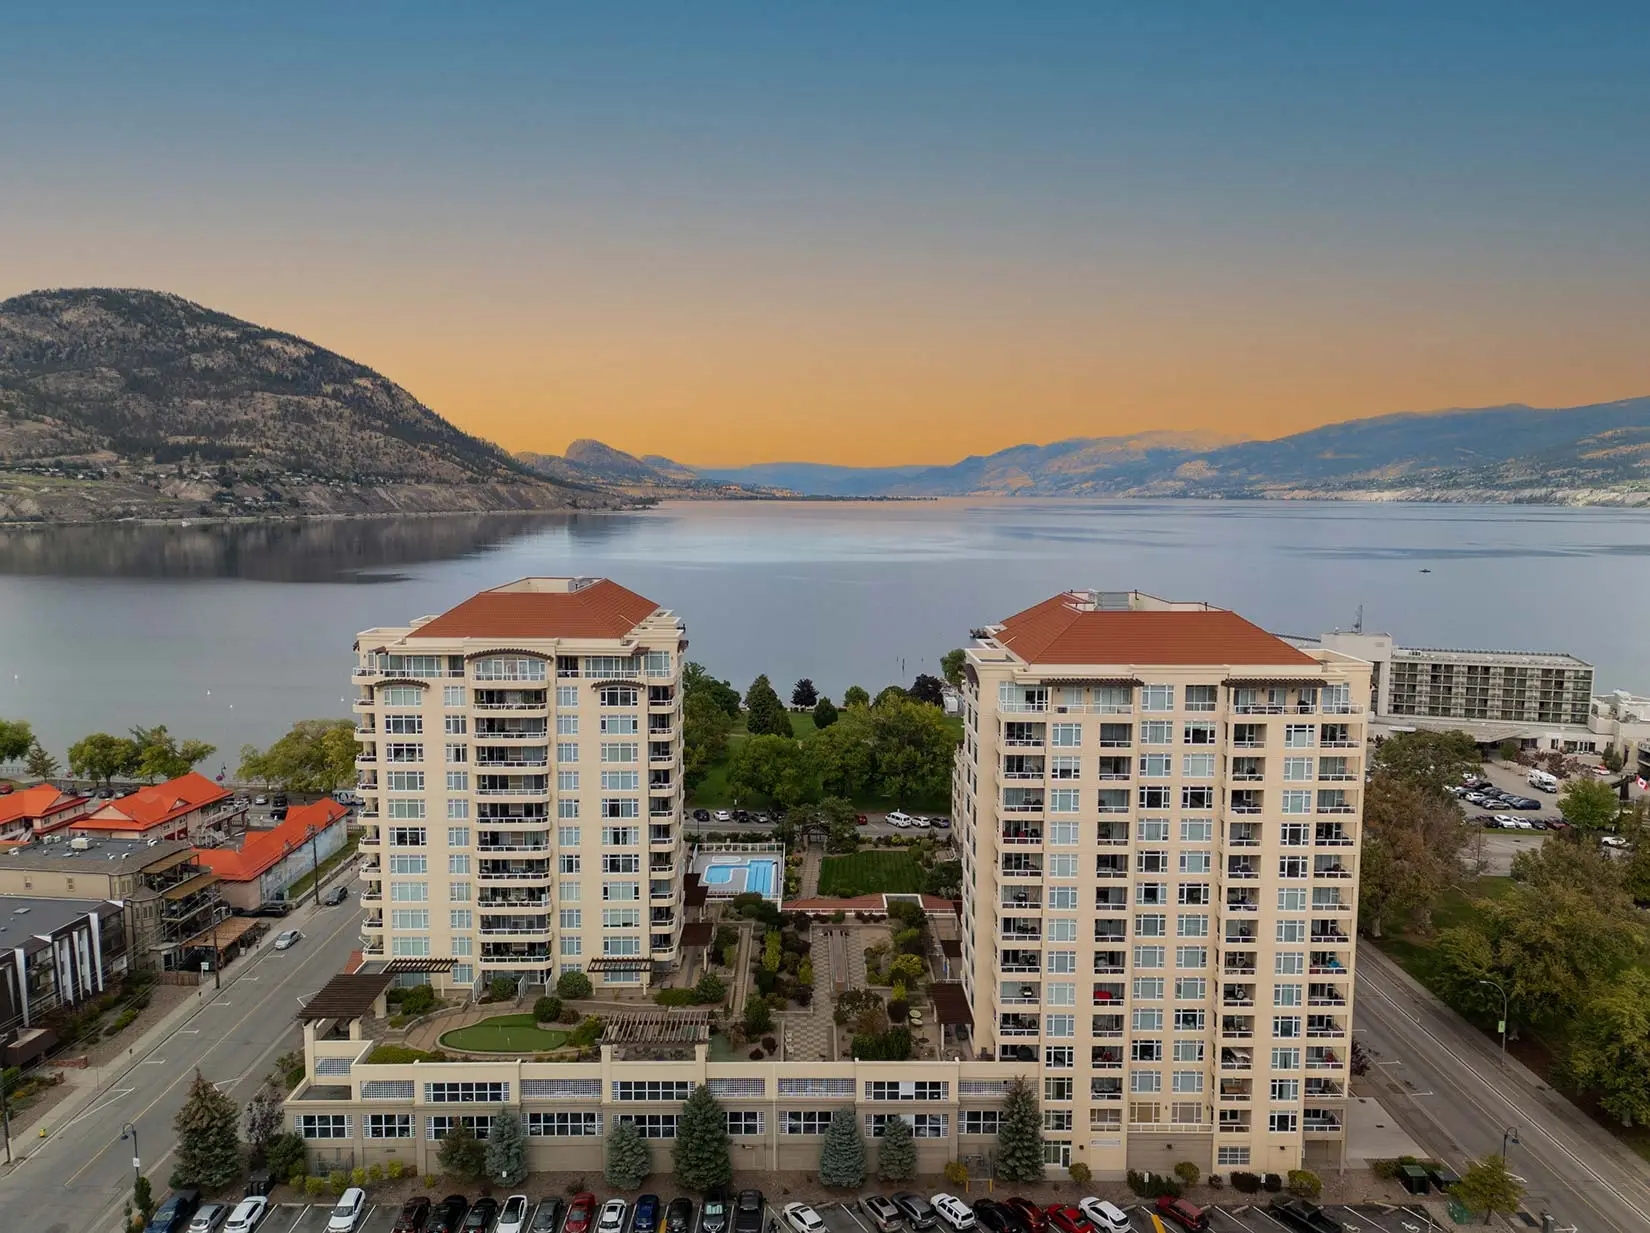
Lakeshore condo towers on Okanagan Lake in Penticton

Local Strata
& Condo Expertise

Penticton's unique lakeside and vacation market features specific lending variables that standard bank employees often miss. Out-of-town underwriters regularly stumble over local strata form analysis, self-managed complexes, and restrictive rental or age bylaws. We specialize in regional condo financing, maintaining direct access to lenders who understand the unique residential and townhome developments across the valley.

By receiving the HomeBrew monthly report from the HomeHappy Team @ Canadian MOrtgage Experts, you can track your home's value, your mortgage, your equity, and whether making a change makes sense.

Renewal Review & Rate Hold

Leaving your mortgage untouched until renewal day can be a five-figure mistake. We watch the market for you, send you a monthly report on your home and mortgage, and start your renewal review early enough to hold a rate up to 120 days before maturity. If high-interest debt is squeezing your budget, we can roll it into one mortgage payment to free up your monthly cash flow.

See What the HomeBrew Strategy Looks Like Across Penticton

While the big banks look at local real estate through rigid corporate filters, our HomeBrew reports track your local market month by month.

Take a look through our Penticton portfolio gallery below to see the diverse property markets where we actively manage equity, protect monthly cashflow, and guide homeowners all the way to mortgage freedom day.

Skaha Hills leasehold. Skaha Hills sits on Penticton Indian Band land under a long-term lease, and that changes who will lend. Many lenders won’t touch lease land at all. We know the ones who will, so a Skaha Hills file goes to the right lender the first time, not through a string of declines.

Unlock Your Custom HomeBrew Analysis

Standard bank apps give you basic numbers, but they don’t give you a strategy. As your Penticton mortgage broker team, we look far beyond basic interest rates with our HomeBrew wealth-tracking platform. Every month it tracks South Okanagan property values, your true net equity cushion, and proactive debt-restructuring options, well before renewal pressure peaks.

Penticton Mortgage Questions We Actually Get Asked

Skaha Hills is on leased land. Can I get a mortgage there?

Yes, but it is a different mortgage from a freehold purchase, and the differences decide your lender before anything about your income does.

Leasehold on First Nation land is no longer a Westside-only question in the Okanagan — Penticton has a growing number of these properties, and the financing rules are the same wherever the land sits. Fewer lenders participate in leasehold at all, and those that do generally want the amortization to finish comfortably before the lease term ends.

That’s the part that catches people. On a lease with limited years remaining, the maximum amortization shortens, which raises the payment and reduces what you qualify for — on identical income and an identical purchase price. Down payment expectations are often higher, and appraisal takes more care because the comparable sales pool is smaller.

So the first two facts to establish on any leasehold property are the remaining lease term and whether the lease is prepaid. Those determine your lender list before your file is even read. We do these routinely in West Kelowna and the same approach applies here.

Will I have to pay the speculation and vacancy tax on a Penticton property?

Quite possibly, and this catches out-of-town buyers more than anyone — particularly people buying a second home or a future retirement property they don’t intend to occupy full time yet.

The City of Penticton is a designated taxable area for BC’s speculation and vacancy tax, as is Summerland and, to the north, Kelowna and West Kelowna. Being in a taxable area doesn’t automatically mean you owe the tax — most owners are exempt — but it does mean the rules apply to you.

Three things worth knowing:

  • The rates doubled for 2026. BC residents, Canadian citizens and permanent residents now pay 1% of assessed value on a vacant or underused property, up from 0.5%. Foreign owners and untaxed worldwide earners pay 3%, up from 2%. The offsetting credit for BC residents rose to $4,000.
  • Everyone in a taxable area must declare by March 31, including people who are fully exempt. Miss the declaration and you’re assessed automatically at the maximum rate.
  • The common exemptions are principal residence and long-term tenancy — generally requiring the property to be rented at least six months of the year in periods of a month or longer. Short-term rentals don’t satisfy it, which is exactly the trap for a recreational property being run as a nightly rental.

One exception worth knowing if you’re comparing properties: reserve lands, treaty lands and the lands of self-governing Indigenous Nations sit outside the taxable areas entirely. So a leasehold home can fall outside this tax while a freehold house nearby does not.

None of this changes whether you can get a mortgage. It changes what the property costs to hold, which is the number that matters across a five-year term. Check any specific address against the province’s list, and take the detail to your accountant.

Can I count short-term rental income on a Penticton property?

The zoning question and the mortgage question have different answers, and it’s the second one that decides your approval.

Short-term rental rules in BC now come in two layers — the provincial framework and the municipal bylaw — and they have changed more than once in the past two years. Kelowna opted out of the provincial principal-residence requirement effective June 1, 2026; other Okanagan communities sit under different arrangements. Before you rely on nightly-rental income for anything, confirm the current position for that specific address with the City and with the province, not with a listing description.

The mortgage answer is more conservative regardless of what the bylaw permits. Most lenders discount short-term rental income heavily or won’t count it at all, and those that do generally want a documented operating history rather than a projection. A revenue estimate prepared for a listing is not income, and no lender treats it as such.

So a property can be perfectly legal to operate as a short-term rental and still not qualify you for a dollar more than it would as a plain residence. Treat nightly-rental revenue as upside if it arrives — not as the income that gets you approved.

I’m retiring to Penticton. Will my age or pension income affect approval?

Age itself is not a factor and cannot lawfully be one. Income is — and retirement income is read very differently from one lender to the next.

Defined-benefit pension income is generally treated well. CPP and OAS are universally accepted but rarely sufficient alone. RRIF withdrawals are where lenders diverge most sharply: some count an established draw in full, others discount it, and a few will look at the underlying asset base instead. The same retirement package can produce materially different approvals depending on who reads it.

If a bank has already declined you, that’s a statement about that lender’s method rather than about your finances — here’s what to do next.

My income is seasonal. Does that work in the South Okanagan?

It has to, because a great deal of Penticton’s economy runs that way — tourism, hospitality, wineries, orchards, construction.

Lenders want a pattern rather than a peak. Typically that means a two-year history in the same field with income averaged across the whole year. The common mistake is applying in the strong months and expecting those months to represent the year. Bring the full picture, including the quiet season, and the file gets read properly the first time.

Does a smaller market change how the property gets appraised?

It can, and it’s worth anticipating rather than discovering.

Appraisals rest on comparable sales. In a smaller market with fewer transactions — and especially on unusual properties like acreage, orchards, waterfront, leasehold, or homes with an unusual layout — there may simply be fewer genuine comparables. That can mean a longer appraisal turnaround, a wider range of possible values, or a value that comes in under an accepted offer.

None of that is a reason to avoid the market. It’s a reason to build a realistic appraisal timeline into your subject removal dates, particularly outside Penticton proper in Summerland, Naramata, Okanagan Falls, and further south.

Where Else We Work

South Okanagan searches rarely stop at one town. Plenty of our Penticton files also look at Kelowna and West Kelowna to the north, and we see families arriving from the Lower Mainland chasing space and a slower pace. The financing questions follow the property type, not the postal code.
Stop Stressing over Bank Math. Get the Monkey Math App!

Monkey Math, The HomeHappy Team's mortgage app for your phone

Redefine Mortgage Math. Put the Simplicity in Your Pocket.

Love the calculators on our site? Take the effortless simplicity of Monkey Math with you…

Scan or Tap to Download (FREE)

BC Mortgage Experts

Let's chat!

Whether you want to meet up for a coffee downtown on Main Street next time I’m in town, or connect from the comfort of your own living room... Let’s sit down and dial in your South Okanagan property plan. Click here to book!

Penticton Mortgages: Your Bank, a Transactional Broker, or HomeHappy

Where you get your mortgage changes what happens to it. Here is how the three options compare for a Penticton purchase or renewal.

Your bank or bank repA transactional brokerHomeHappy
Lenders you can reachThe bank’s own products only, from a branch or a mobile mortgage repSeveral lenders, depending on the brokerage50+ lenders from one application
Leasehold, such as Skaha HillsOne policy, and fewer lenders take leasehold at allDepends on the broker’s lender listWe know which lenders take leasehold and what they want, such as an amortization that ends before the lease does
Short-term rental or seasonal incomeOne policy, and often cautious or no credit for short-term rental incomeVariesWe match it to a lender that will count a documented history of it
Pre-qualificationOften a rate hold on numbers you stateVariesDocuments reviewed first, answer 24 hours after a complete package
After closingThe mortgage sits until the renewal letterFile closed, paid, forgottenGoes into HomeBrew, with a strategy conversation by 6 months before renewal
How you meetA branch, or a mobile rep who comes to youVariesVideo or phone, from our West Kelowna base
Illustrated badge of Michael Lloyd, mortgage expert since 1999, above the Penticton channel

Why Choose HomeHappy as Your Penticton Mortgage Broker?

Most lenders treat a mortgage as a one-time transaction, disappearing the moment your papers are signed. As your dedicated Penticton mortgage broker, we play the long game—staying by your side to actively manage, optimize, and restructure your debt from day one all the way to your ultimate mortgage freedom day.

By combining our multi-decade track record in the valley with proactive financial strategy, we ensure your mortgage continuously evolves to protect your cashflow and maximize your wealth for the life of your loan.

The HomeHappy Team @ Canadian Mortgage Experts

Address:
3954 Beachview Drive West Kelowna, BC V4T2K1
URL: www.homehappy.ca/penticton-mortgage-broker
HappyChat, the monthly eNewsletter from The HomeHappy Team @ Canadian Mortgage Experts: a quick synopsis of the mortgage rate and product world.

Join our Monthly e-Newsletter

Website HappyChat Sign Ups