Navigating the fast-moving real estate landscape of the Fraser Valley requires a strategy designed for a highly competitive, rapidly growing city. As a dedicated Surrey mortgage broker team backed by over 260 verified client reviews on Google and Rate My Agent, we believe securing a home shouldn’t mean sitting in stuffy bank lobbies or settling for rigid corporate templates.
The big banks and out-of-town call centres treat Surrey like any other postal code. Lenders don’t. A transit-oriented condo near Central City or Guildford, a family home in South Surrey or Cloverdale and a house with a basement suite can each get a different answer from the same lender. With access to 50+ lenders, we know which ones read your kind of property the way you need it read, and we build the mortgage around protecting your monthly cashflow.
In a market this competitive, your financing has to hold up before you write the offer. We don’t hand you an automated certificate. We verify your documents and fully pre-qualify you before you start touring open houses with your Realtor, so you know your real buying power under the federal stress test, and listing agents know your offer is backed by a broker who has been funding Lower Mainland mortgages since 1999.
We know how Surrey’s secondary suite bylaws affect your qualifying rental income, how local property boundaries can affect a bank appraisal, and how to structure complex files so lenders can sign off quickly. That local knowledge goes into every Surrey file we work on.
In Surrey's fast-moving market, an unverified offer is a losing offer. Our deep upfront pre-qualification process fully audits your file before you write an offer, removing underwriting friction down the road. Walk into open houses in Fleetwood or Guildford with the backing of a broker who has been funding mortgages since 1999.
Why settle for a basic, transactional bank rate? Our HomeBrew system treats your mortgage as a vehicle for long-term wealth building. We pair the experience of the leader who took Canadian Mortgage Experts past $14 billion in closed mortgages (2010–2025) with a personal, whole-picture strategy designed to optimize your equity and shield your net worth.
Leaving your mortgage untouched until renewal day can be a five-figure mistake. We watch the market for you, send you a monthly report on your home and mortgage, and start your renewal review early enough to hold a rate up to 120 days before maturity. If high-interest debt is squeezing your budget, we can roll it into one mortgage payment to free up your monthly cash flow.
A couple bought a detached house together with a parent, three borrowers on one mortgage. Multi-generational buying is common in Surrey, and it changes how a lender adds up incomes and debts, so the lender has to be chosen with all three people in mind.
In another file, a couple sold their long-time home and bought a South Surrey townhouse using a reverse mortgage, which meant no monthly mortgage payments in retirement. Most people don’t know a reverse mortgage can be used to buy.
Clients stay with us for decades because we keep showing up after closing. Since 1999, as a Surrey mortgage broker team, we have helped thousands of families secure their homes, protect their equity, and find better options than their bank offered.
But don’t just take our word for it—read the real, unfiltered experiences from local homeowners who have worked with us.

When monthly cashflow is tight, the natural instinct is to freeze, wait, and hope the market shifts. But in the fast-paced Fraser Valley market, relying on a proactive Surrey mortgage broker to restructure your debt is almost always more profitable than passive waiting.
Closing your eyes to a looming renewal or absorbing months of high-interest credit card and line-of-credit debt to keep up with your housing costs isn’t a strategy—it’s an expensive holding pattern.
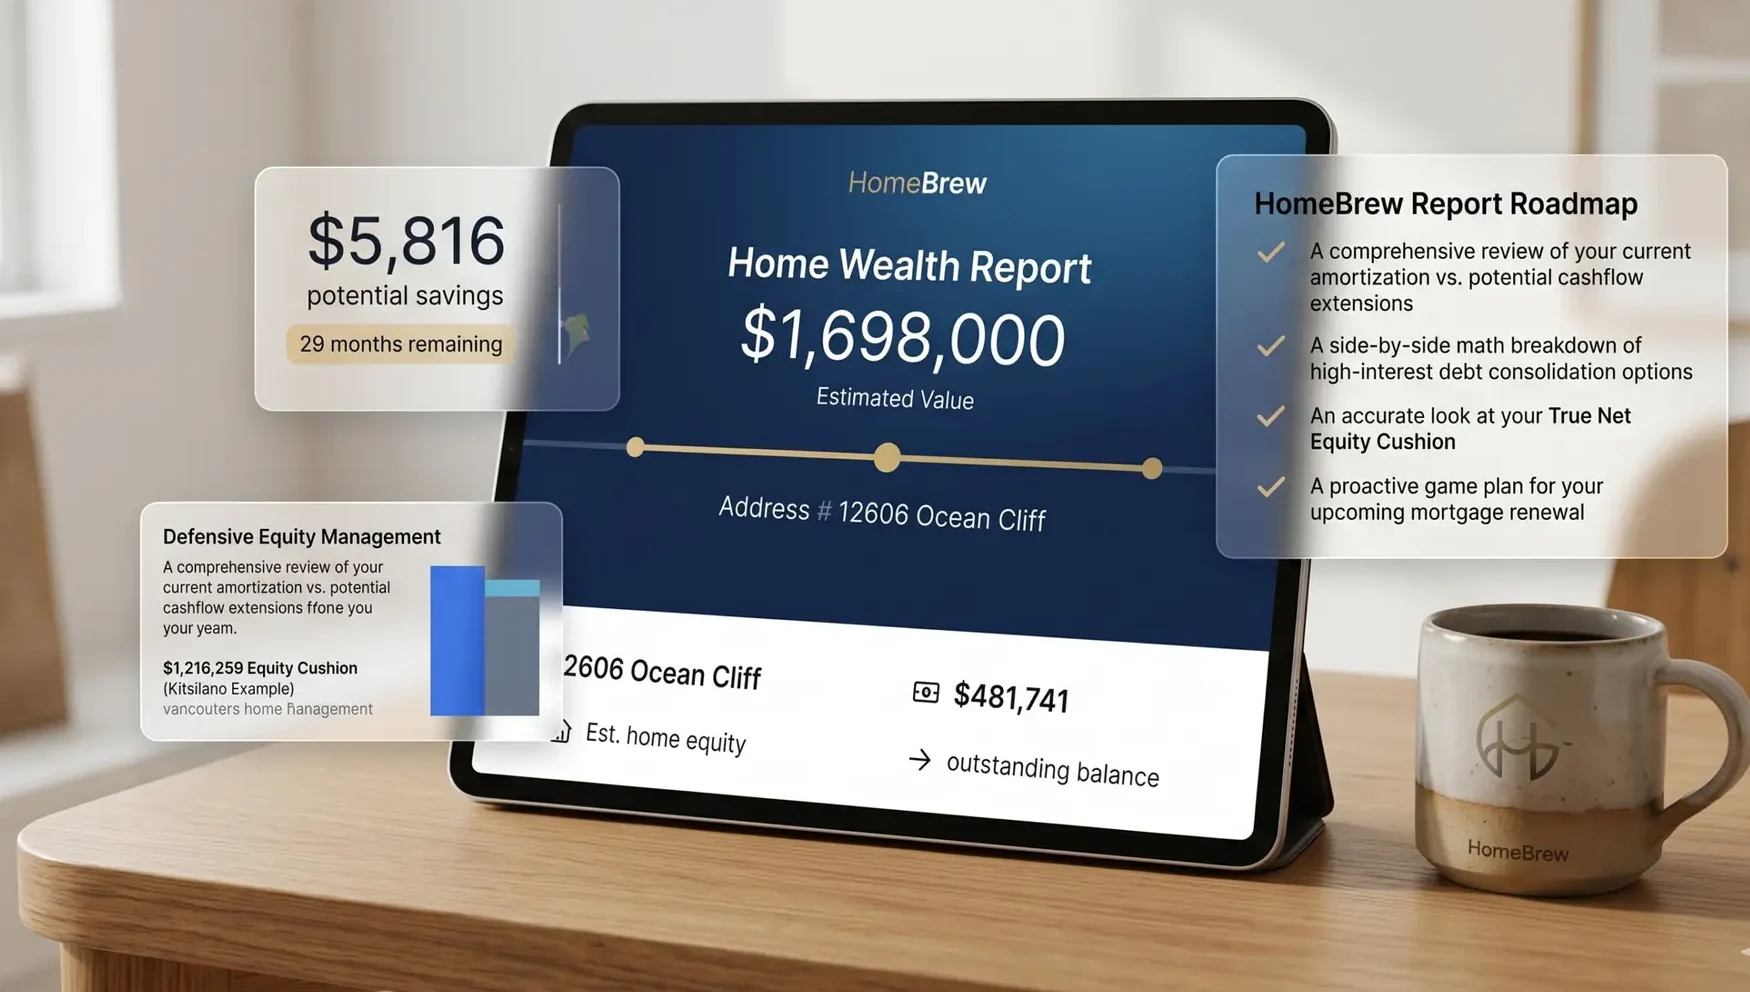
With a custom HomeBrew Analysis, we pull back the curtain on your options before pressure peaks. Even if local property values have shifted, your mortgage remains a powerful tool that can be stretched, consolidated, or optimized to instantly lower your household overhead and protect your hard-earned equity.
Your Personalized HomeBrew Roadmap
✓ A comprehensive review of your current amortization vs. potential cashflow extensions.
✓ A side-by-side math breakdown of high-interest debt consolidation options.
✓ An accurate look at your True Net Equity Cushion (e.g., using Surrey real estate benchmarks).
✓ A proactive game plan for your upcoming mortgage renewal.

Let’s Map Out Your Cashflow Recovery Plan Together
No. We work by video and phone across British Columbia, and most Surrey clients never meet us face to face. The application, document upload, and signing are all digital and secure. Practically, that means the conversation happens when it suits you — evenings and weekends included — instead of when you can get across town in traffic. If you’d rather sit down with someone in a branch, that’s a fair reason to choose a local branch instead, and we’ll say so.
Usually yes, and this matters more in Surrey than in most BC markets because suites are so common here. But lenders treat that income in two quite different ways. Some use a rental offset, subtracting the rent from your housing costs. Others use a rental add-back, adding a percentage of the rent to your income. The same suite, the same rent, and the same borrower can produce materially different approval amounts depending on which method the lender uses.
Two things decide whether it counts at all: whether the suite is legal and registered with the City of Surrey, and whether you can document the rent. An unauthorized suite isn’t automatically fatal, but it narrows the lender list considerably. Bring us the details before you write an offer, not after.
Three things. GST applies to new construction and isn’t part of your mortgage, so it needs planning for separately. Completion dates on presale and new construction often sit well beyond a standard rate hold, which means the rate you’re quoted today may not be the rate you close at — some lenders offer extended holds for exactly this reason, and knowing which ones matters. And lenders underwrite presale contracts differently from resale purchases, so a pre-approval taken against a resale assumption can fall apart on a presale file.
Honestly, not in any way that should affect your choice. Mortgage rules are federal, BCFSA licensing is provincial, and lenders price the same across the Lower Mainland. What does differ is property type. Surrey has more suites, more new construction, and more acreage on its eastern edge than Vancouver does — and lender appetite varies sharply on all three. The useful question isn’t where your broker sits. It’s whether they know which lender reads your kind of property the way you need it read.
A pre-approval is a rate hold and a rough estimate, not a commitment to lend. It usually hasn’t involved anyone verifying your income documents or looking at the property. That’s why pre-approvals fall apart at offer time — the file gets underwritten properly for the first time after you’ve already committed.
Two things worth doing: find out whether your pre-approval was fully underwritten or automated, and find out what the penalty calculation is on that specific product. A lender pricing slightly better with a penalty calculated on posted rates can cost you far more in year three than the rate saved in year one.
Surrey rarely sits on its own in a search. Buyers here regularly end up looking at Langley for more space, White Rock for the coastal move, or Vancouver when work pulls them west. The financing questions change with the property type more than they change with the postal code, and we cover all of it from one file.
Where you get your mortgage changes what happens to it. Here is how the three options compare for a Surrey purchase or renewal.
| Your bank or bank rep | A transactional broker | HomeHappy | |
|---|---|---|---|
| Lenders you can reach | The bank’s own products only, from a branch or a mobile mortgage rep | Several lenders, depending on the brokerage | 50+ lenders from one application |
| Basement suite income | Uses its own method for counting suite rent | Depends on the broker’s lender list | Lenders count suite rent in different ways, and the same suite can give a materially different approval amount, so we choose among them |
| A presale or new build | A standard rate hold, which may run out before completion | Varies | Some lenders offer extended holds for long completion dates, and we know which |
| Pre-qualification | Often a rate hold on numbers you state | Varies | Documents reviewed first, answer 24 hours after a complete package |
| After closing | The mortgage sits until the renewal letter | File closed, paid, forgotten | Goes into HomeBrew, with a strategy conversation by 6 months before renewal |
| How you meet | A branch, or a mobile rep who comes to you | Varies | Video or phone, evenings and weekends included |
Most lenders treat a mortgage as a one-time transaction, disappearing the moment your papers are signed. As your dedicated Surrey mortgage broker, we play the long game—staying by your side to actively manage, optimize, and restructure your debt from day one all the way to your ultimate mortgage freedom day. By combining our experience as an independent BC broker since 1999 with proactive financial strategy, we ensure your mortgage continuously evolves to protect your cashflow and maximize your wealth for the life of your loan.
Join our Monthly e-Newsletter